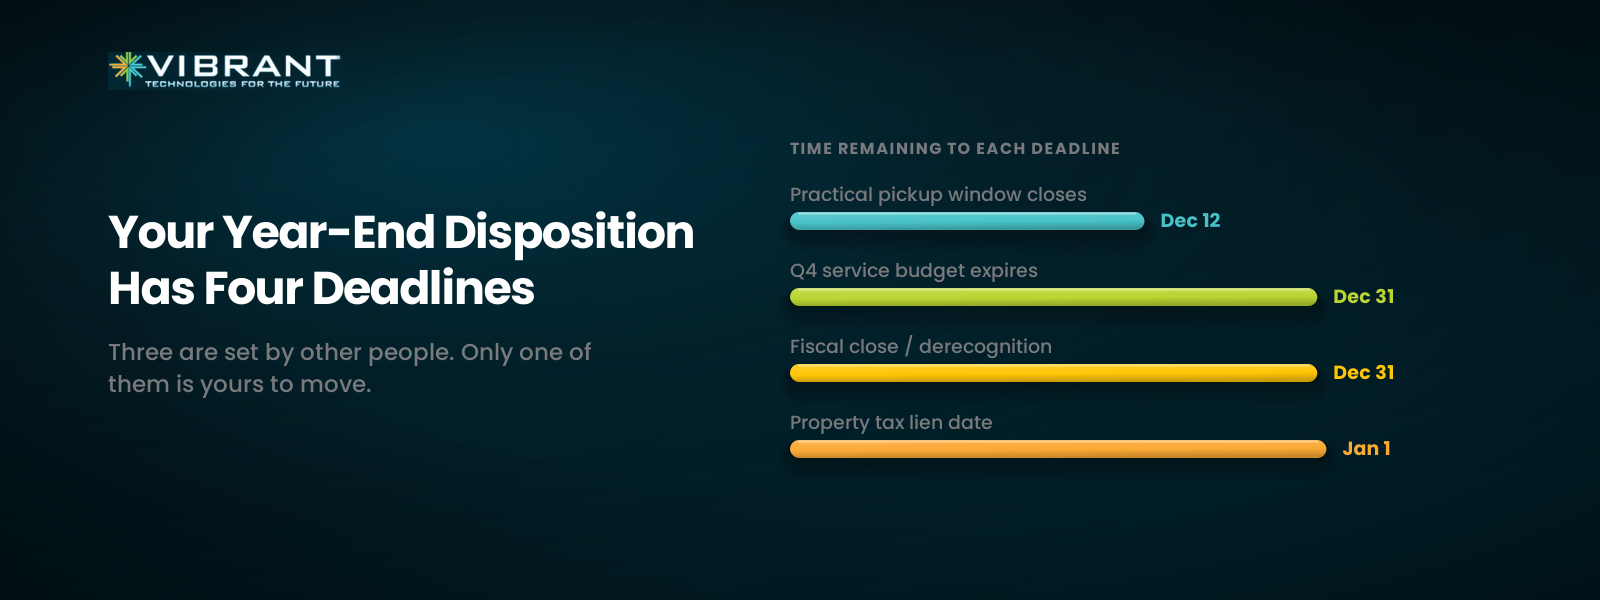
Fiscal close, the property tax lien date, expiring Q4 budget, and December logistics all land in the same eight weeks. Only one of them moves.
Most organizations treat year-end IT disposition as a housekeeping task. Clear the storage room, get the pallets out, start January clean.
That framing costs money, because disposition at year-end isn't one deadline. It's four, they fall within a few weeks of each other, and three of them are fixed by someone other than you.
It's early November. Here's what's actually in front of you.
Deadline One: The Disposal Has to Post in the Right Period
An asset comes off the books through derecognition, and derecognition has to land in the correct fiscal period. Equipment that physically leaves your dock on December 18 but isn't documented until February doesn't produce a December disposal. It produces a reconciliation problem, a gain or loss posted in the wrong year, and depreciation that kept running on hardware that was already gone.
The constraint isn't the pickup. It's the paperwork that follows it. If your provider's serialized reporting takes six weeks, a mid-December collection cannot close out in this fiscal year, no matter how early the truck arrives.
This is the question to ask before you schedule anything: how many business days after pickup does asset-level documentation arrive? If the answer is vague, assume it won't make your close.
Deadline Two: The Property Tax Lien Date
This is the one almost nobody calendars, and it's the hardest of the four.
In many jurisdictions, business personal property is assessed based on what you owned on a specific date — and in California, that date is 12:01 a.m. on January 1, set by statute. Assessors there are explicit about both sides of it. Property disposed of before the lien date is excluded from the statement, and its original cost comes out of the year of acquisition. Property you owned on the lien date is assessed for the full upcoming fiscal year, even if you disposed of it the following day.
Read that again with a storage room full of retired servers in mind. Equipment that is physically gone but still on your schedule gets taxed. Equipment that leaves on January 2 gets taxed for the whole year. Equipment that leaves on December 29, and is documented, does not.
Two important caveats. Assessment dates and rules vary by state and locality — some states don't tax business personal property at all — so confirm your own jurisdiction rather than assuming January 1. And the saving comes from the asset actually being disposed of and correctly reported, not from moving pallets to a different room. This is a conversation for your tax team, not your IT team, and it's worth having before December.
Deadline Three: Q4 Budget That Expires
Service budget doesn't roll over in most organizations. If there's money allocated this year for decommissioning, data destruction, or facility work, it either gets used or it disappears on December 31.
There's a related asymmetry worth understanding. Disposition that generates recovery revenue often isn't a spend at all — it's a settlement coming back to you. But the work that surrounds it, on-site sanitization, deinstallation, logistics for low-value equipment, does cost money. Year-end is when that budget exists.
Deadline Four: December Logistics Are Not November Logistics
The last two weeks of December are the worst time to move freight. Carriers are at peak capacity on consumer volume, your loading dock is running a holiday schedule, facilities staff are on leave, and the people who need to sign off on an asset list are out. Add a winter weather day and a scheduled pickup becomes a January pickup.
Processing facilities also have year-end queues. A pickup scheduled for December 22 may not be received, audited, and reported until well into January, which puts you back in the Deadline One problem.
The practical consequence: the usable window for year-end disposition closes earlier than the year does.
Working Backward From December 31
Here's a realistic timeline from where the calendar sits now.
Early to mid-November — decide what's going. Pull the list. Equipment already decommissioned and staged, hardware coming out of a Q4 refresh, anything in a facility that's closing. Get serial numbers, not counts. If you don't know what's in the storage room, that's this week's job, not December's.
Mid-November — get quotes and pick a provider. Ask for valuation and for reporting turnaround in business days. Ask whether they can commit to a December pickup and a December report. Get the authorization signed while the people who sign things are still at their desks.
Late November to early December — schedule the pickup. Earlier than feels necessary. A collection in the first two weeks of December leaves room for a weather day, a rescheduled dock, and a missing approval.
Through mid-December — reconcile as reporting arrives. Match serialized documentation against the fixed asset register as it comes in, not in one pass at the end. Discrepancies take time to resolve and the people who can resolve them are about to go on holiday.
By December 31 — post the derecognition. Register updated, depreciation stopped, disposal recorded in period, and the property tax schedule corrected for the coming assessment.
January — close the file. Certificates archived to your retention schedule, settlement reconciled, and any remaining items scheduled for Q1 rather than left in limbo.
If you're starting this in the second week of December, the honest answer is that you're planning a Q1 disposition with a December pickup. That's a fine outcome — it's just a different one, and it's better to know now than to discover it during close.
What Goes Wrong Specifically at Year-End
The rush quote. Pressure to move fast is how whole-unit numbers get accepted without anyone asking what the configuration was worth.
The undocumented December pickup. Equipment leaves, everyone exhales, the paperwork arrives in February and reconciles to nothing.
The partial list. Half the fleet goes because it was easy to find. The other half stays in the storage room for another year, aging and still on the books.
The skipped authorization. In a hurry, the same person approves, executes, and verifies the disposal. That's the control gap your auditor looks for, and year-end pressure is exactly when it happens.
The staging-room shuffle. Moving retired equipment out of sight is not disposition, and it does not change what you own on an assessment date.
The Short Version
Three of the four deadlines are set by other people. The one you control is when you start.
Eight weeks is enough time to inventory, value, collect, document, and reconcile a year-end disposition properly. Three weeks is enough time to move pallets and sort it out later, which is how equipment ends up gone from the floor and present on the books — the exact problem we wrote about in Chain of Custody Is a Finance Problem.
Vibrant Technologies has provided secure, documented IT asset disposition since 1998, and is R2v3 certified. If you have equipment that needs to be gone and accounted for before your fiscal year closes, we can tell you what's realistic from here. Request a valuation
This article is general guidance and is not tax, accounting, or legal advice. Property tax assessment dates, reporting requirements, and the treatment of asset disposals vary by jurisdiction and by organization. Confirm the specifics with your own tax and accounting advisors.